Financial Planning For Executives Between 55 and 65 Coordinating the Decade Before Retirement.
Between 55 and 65, your tax, estate, and retirement decisions stop being separate. §72(t) distributions, Roth conversions, capital gains harvesting, Medicare timing, and Social Security claiming all share the same calendar, and most advisors solve them one at a time. I solve them together.

Trusted Partners:

You are worried, do I have all of this right?
You’ve been saving, investing, checking all the boxes. But you still have questions. Do I have everything in place? Have I set myself up and my family for long term success? I wish I could talk to someone that cared about me.
A CPA, an attorney, and an advisor can each give good advice while nobody looks at the whole picture.
Most advisors treat the ten years before Medicare as two separate problems. I treat them as one coordinated decision: tax, estate, and retirement planned together, not handed to specialists in isolation.
Concentrated stock and equity compensation can be difficult to unwind without a large tax cost.
Concentration didn't build overnight, and it shouldn't unwind overnight either. Sequencing the exit across the decade (using low-bracket years, the 0% capital gains window, and coordinated tax timing) changes what it costs you.
It can be hard to know whether you are making the most of your last working decade before retirement.
§72(t) distributions, Roth conversions, IRMAA timing, and Social Security claiming all share the same calendar. Most advisors solve them one at a time, as you encounter them. That's usually too late for the first few.
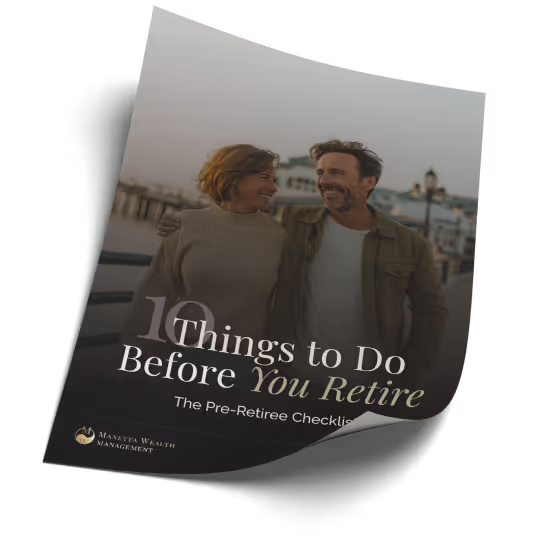
Download Your Free Checklist.
Learn the 10 most important steps to prepare for retirement so you can move forward confidently with a plan that fits your life.
At Manetta Wealth, We’re All in on You.
We’ll handle the full picture—so you’re never left wondering if something’s been missed. One advisor, always in your corner.
Fiduciary Advice—Always.
We’re legally and ethically required to act in your best interest—not a bank’s or a product manufacturer’s. No commissions, no hidden incentives. Purely, relationship-driven advice.
Everything in One Place.
Through Altruist, all your financial data lives in one platform—investments, performance reporting, and planning tools working together. No more chasing information across accounts.
A Real Relationship.
We stay engaged on a far more regular basis—not just each quarter or when the market moves. You’ll always get an advisor who cares to know your name, your goals, and your current situation.
Get To Know Manetta Wealth Management.
Manetta Wealth Management is an independent, fee-only advisory firm based in San Francisco, California, built to serve executives and senior professionals between 55 and 66 who need their tax, estate, and retirement decisions coordinated, not handled one at a time.
Getting Started Is Easier Than You Think
We keep our process pretty straightforward. Here’s what working with us actually looks like—in just 3 simple steps.
- 01.Are We A Fit?
Understand Your Coordinated Decade.
We map where you stand in the 55-to-65 window and which decisions: Roth conversions, concentrated stock, IRMAA timing, and more which are approaching important milestones.
- 02.Are We A Fit?
Integrate All the Levers.
Tax timing, capital gains harvesting, Roth conversions, and Medicare premium coordination, all sequenced together, not decided one at a time. It is a "coordinated" campaign.
- 03.Are We A Fit?
Execute Across the Decade.
The plan runs across the full decade: it means tax timing, Roth conversions, and estate coordination executed in sequence, reviewed on an ongoing basis, not decided once and left alone. Start with an estate plan review checklist. This is the moment you get it right. Let me help you get there.
Are We a Fit?
We work best with clients who see the decade before retirement as one coordinated decision, not a series of isolated problems.
Executives and senior professionals, typically 55 to 66
$500,000 to $2 million in investable assets
Holding concentrated stock, equity comp, or both
Navigating Roth conversions, IRMAA timing, and Social Security in the same window
Looking for a fee-only, independent fiduciary, not a product salesperson
Ready to plan across tax, estate, and retirement as one picture
Find Your Starting Point
Explore planning considerations for professionals with complex compensation or business owners coordinating personal and business finances. You can also review our services and pricing.
If that sounds like you, let’s talk.
Schedule a Free AssessmentReady to See If We’re a Fit?
Grab 30 minutes with us—we’ll talk through where you stand today, where you’d like to be, and together figure out if we’re the right fit for each other.